You may have seen the headlines saying mortgage rates have climbed to the highest point since January 2025. And if that’s left you reluctant to buy a home, here’s what you need to remember:
That’s not necessarily the number you’d get.
It’s a common misconception that the rate you see in the headlines is the same one you’d get when you buy. The truth is, mortgage rates shift often, and the rate you actually end up with can vary significantly based on your financial situation, loan type, and other factors.
If you’re keeping an eye on Northern Colorado mortgage rates, remember that national headlines only tell part of the story. Your actual rate will depend on your individual financial profile and the loan options available to you.
What Determines Your Real Rate?
Advertised rates and “real rates” aren’t always the same. That’s because real rates are based on your specific situation, which includes your overall finances and goals. The rates you see in the headlines can’t possibly reflect that.
That’s why only a lender can tell you what your real rate will be. To figure out your unique number, they’ll look at:
- Your credit score: Your credit score includes your payment history (if you’ve made late payments – and how often), credit utilization (are your accounts maxed out, or do you have available credit?), and the length of your credit history (how long have your accounts been open?). For example, someone with an exceptional credit score may qualify for a better rate.
- Your debt-to-income ratio (DTI): This is calculated by dividing your monthly debt payments by your monthly income before taxes to come up with a percentage. The higher your DTI, the higher your rate could be.
- The down payment size and Loan-to-Value (LTV): Your down payment is the percentage of the home’s price you will put down. The LTV is the percentage of a home’s sales price that equals your mortgage.
- The type and term of loan program options: Your loan officer will walk you through different loan options based on what you qualify for. Mortgage rates can vary between different loan products and programs.
If you’re thinking about buying a home in Northern Colorado, understanding these factors early can help you create a more realistic budget before you begin touring homes.
Even after you find a home you love, other things can have an impact too. For example:
- A mortgage rate buydown: This helps you get a lower mortgage rate, and by extension, a lower monthly payment, by paying an upfront cost. Sometimes a seller, builder, or another party may even offer to cover that cost themselves as an incentive for you to buy.
- Seller concessions: Sellers are allowed to pay buyer closing costs according to most loan program guidelines. Seller-paid closing costs can add up to thousands of dollars, which can free up some cash for you to increase your down payment, pay down debt, or make other financial adjustments to try to get a better rate.
There’s a lot that can ultimately have an impact on your actual rate.
Other Factors That Can Affect Your Monthly Payment
Even after you find a home you love, there may be additional ways to influence your financing.
Mortgage rate buydown: A rate buydown can reduce your mortgage rate, which may lower your monthly payment. In some transactions, a seller or builder may agree to contribute toward that cost.
Seller concessions: Depending on the loan program and transaction, sellers may be able to contribute toward a buyer’s closing costs. That can help preserve cash for other financial priorities.
For Northern Colorado home buyers, these types of negotiations can be especially valuable when comparing the overall cost of one property against another.
Your First Step? Getting Pre-Approved.
If you want to know if your number could be higher or lower than the headlines on social, you need to talk to an expert. A simple conversation with a loan officer can help you determine when you’ll be ready to buy, how much you can borrow, and of course, what your real rate will be.
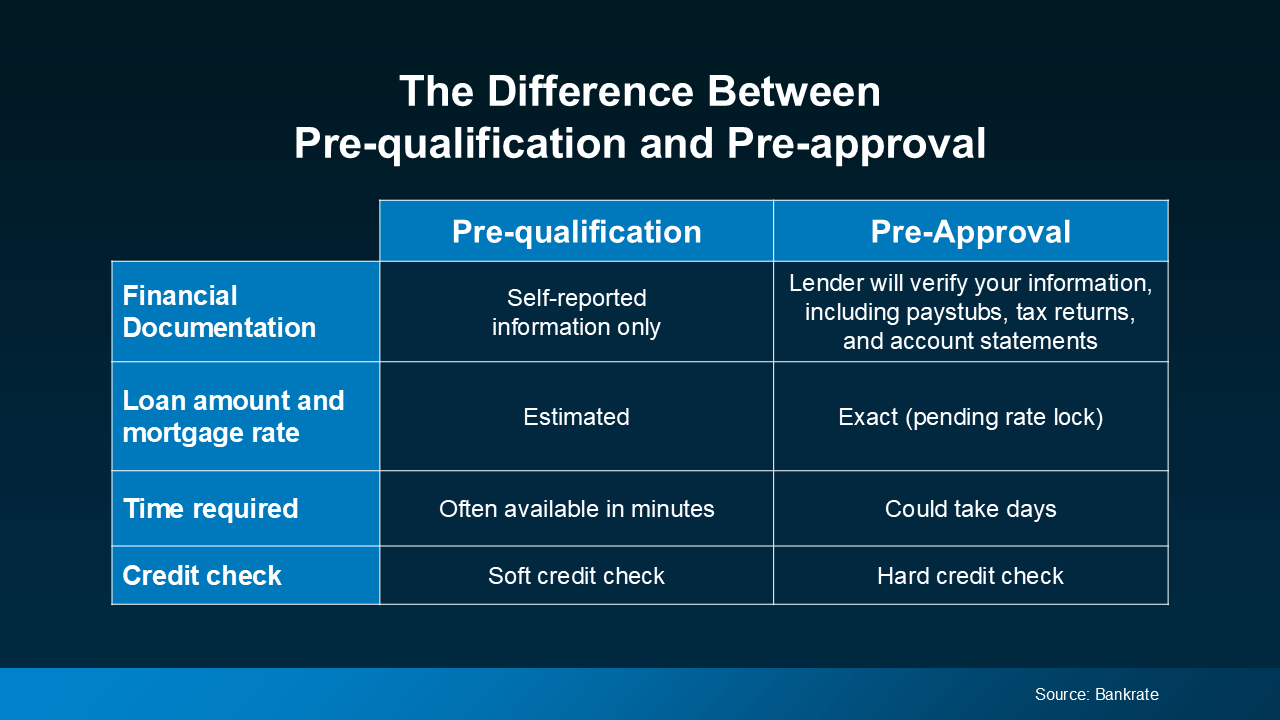
Your lender may recommend a pre-qualification and pre-approval:
- Pre-qualification is a general estimate of what you might be able to borrow based on self-reported information.
- On the flip side, pre-approval is actually a conditional commitment from a lender based on verified information.
Just know that, of the two, the pre-approval process gives you a more accurate picture of your options than pre-qualification. Bankrate gives a quick comparison so you can see why:
How To Get Ready for the Conversation
Ask your lender what documents you’ll need to gather for that conversation. And keep these questions in your pocket too. They’re good things to go over when you talk:
- What will I gain or lose by waiting to buy a home for 3, 6, or 12 months?
- Will I get any tax advantages by buying a home – and what are they?
- What’s the benefit of buying a home and starting to build equity now versus waiting? And how does that impact my finances in the long run?
- How will rate changes in either direction affect me?
Once you find out your rate, maybe you can buy now. Or maybe you still need to wait. But at least you’d know your options and can make an informed decision.
Questions To Ask Your Lender
When you meet with a lender, consider asking:
- What could I gain or lose by waiting 3, 6, or 12 months to buy?
- How would a change in mortgage rates affect my monthly payment?
- Which loan programs might be the best fit for my situation?
- Would a rate buydown make sense for me?
- How much cash should I plan to have available for my down payment and closing costs?
- How would buying now versus waiting affect my long-term financial goals?
Once you understand your actual financing options, you can make a decision based on your numbers rather than national headlines.
Bottom Line
Mortgage rate headlines can make the market feel intimidating, but the rate you see online isn’t necessarily the rate you’ll receive.
If you’re watching Northern Colorado mortgage rates and wondering whether now is the right time to buy, start by speaking with a trusted lender and getting a clearer picture of your financing options.
And when you’re ready to explore homes, I can help you understand the local market, compare properties, and build a strategy for buying a home in Northern Colorado with confidence.